New data gathered by insurers shows that parents continue to be the driving force in a college graduate’s decision to buy short term medical insurance following graduation. Parents pay the premium in more than half of the short term medical insurance policies issues to those in the 21-24 age group. Without this parental financial support, a college graduate is four times more likely to go without medical insurance for a period of two months or more following gradation.
College graduates and their families are often surprised to learn how affordable health plans can be. MedSave.com, a leading provider of low cost medical insurance for college graduates, reports that the average cost of the six most popular health plans to young adults has dropped this year to for the first time in recent history. The price drop is due to the expansion of limited benefit plans rather than a reduction in overall health care costs.
But more health plan choices also means that there is more potential for selecting the wrong coverage. Not surprisingly, the least expensive health plans tend to be the most popular among young adults. This can lead to less than adequate protection. These health plans tend to provide up-front benefits for smaller medical expenses like doctors office visits but offer the least protection for catastrophic risks. It is important that college graduates choose the right plan for their own health situation. It appears that parents may be less likely to be involved in the selection of the insurance than in helping with the cost. Many college graduates are purchasing insurance for the first time and purchase trends indicate that some are making uninformed choices based solely on the cost of coverage or misperceptions of the risk/benefit aspects of insurance choices.
In most cases a high deductible short term medical insurance policy provides a young adult with the best protection at the lowest cost. Most college graduates and other young adults do not benefit financially by purchasing health insurance that covers routine health care like doctors office visits, lab tests and prescription drug costs.
Friday, April 25, 2008

Friday, April 18, 2008
Short term medical insurance in New York
New York residents face a triple threat when it comes to short term health insurance. First, the insurance products used in most states that are specifically designed for this purpose are not available in New York. Second, the coverage that is available is slow; often taking at least a month just to get through the manual application process. Third, the coverage is expensive. No pricing discount is recognized for the likelihood that this insurance will not be in force long enough to accrue catastrophic claims.
The easiest solution is to buy temporary insurance while staying in another state. Insurance issued in another state is valid in New York and allows treatment with any doctor or hospital in the U.S. There is no requirement that the address on temporary health insurance be your permanent residential address. Some New Yorkers residents purchase health insurance while staying at their out-of-state colleges, while at their second home in another state or while on vacation or visiting relatives. The insurance covers treatment while they are away from home as well as with the doctors and hospitals at home in New York. Almost all short term medical insurance is purchased online and most offer immediate download of the policy and insurance ID cards. Most insurance companies allow you to have the policy mailed back to a New York address if you will be returning from your trip soon.
The only other possible alternatives we can offer are:
1. Core Health Insurance – a limited benefit policy that does a fairly good job at mimicking the benefits of major medical insurance
2. International Medical Insurance - for individuals who are not permanent residents of U.S.
3. Inbound Immigrant Insurance – for individuals who have recently moved to the U.S.
If none of these options will work then it is especially important to explore all options to keep, extend or convert prior health insurance regardless of the higher cost.
The easiest solution is to buy temporary insurance while staying in another state. Insurance issued in another state is valid in New York and allows treatment with any doctor or hospital in the U.S. There is no requirement that the address on temporary health insurance be your permanent residential address. Some New Yorkers residents purchase health insurance while staying at their out-of-state colleges, while at their second home in another state or while on vacation or visiting relatives. The insurance covers treatment while they are away from home as well as with the doctors and hospitals at home in New York. Almost all short term medical insurance is purchased online and most offer immediate download of the policy and insurance ID cards. Most insurance companies allow you to have the policy mailed back to a New York address if you will be returning from your trip soon.
The only other possible alternatives we can offer are:
1. Core Health Insurance – a limited benefit policy that does a fairly good job at mimicking the benefits of major medical insurance
2. International Medical Insurance - for individuals who are not permanent residents of U.S.
3. Inbound Immigrant Insurance – for individuals who have recently moved to the U.S.
If none of these options will work then it is especially important to explore all options to keep, extend or convert prior health insurance regardless of the higher cost.
Tuesday, April 15, 2008
Masschussets learns that "insurance is not health care"
A flood of articles in recent weeks discuss the difficulties triggered by Massachusetts' experiment in mandadted health insurance.
The Kaiser Founation published an excellent summry report at http://www.kaisernetwork.org/daily_reports/rep_index.cfm?DR_ID=51517 .
Several other states including California have declined similar proposals. Pols show that the majority of Americans do not wnt mandated health insuance, yet this provision remains a key provision in Hillary Clinton's campaign platform.
The Kaiser Founation published an excellent summry report at http://www.kaisernetwork.org/daily_reports/rep_index.cfm?DR_ID=51517 .
Several other states including California have declined similar proposals. Pols show that the majority of Americans do not wnt mandated health insuance, yet this provision remains a key provision in Hillary Clinton's campaign platform.
Monday, April 14, 2008
Health insurance in a recession
A new article titled "Health Insurance in a Recession" points out some general strategies that may prevent costly mistakes when making desicions about health insurance in financially difficult times.
Tuesday, April 8, 2008
Health insurance scams in Maine

Maine Department of Insurance warns that consumer insurance scams increase during economic downturns. The logo above is designed to help inusrance buyers focus on verifying the legitimacy of dels that seem too good to be true. Consumers are also welcome to use the free independent OnlineAdviser service simply by emailing onlineadviser@medsave.com to verify the legitimacy of any suspected insurance plan. All of the low cost health insurance plans listed at MedSave.com at http://medsave.com/low-cost-health-insurance-listing/me.htm have been verified as legitimate legal plans in Maine.
Monday, September 4, 2006
Risky Business: RSA Puts Their Reputation On The Line
Royal & Sun Alliance Insurance has taken the risky step of going into business with criminal fraudsters Mike Henry and Steve Nichols.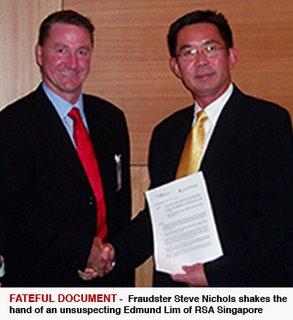
The tie-up is allegedly to sell Interglobal Insurance to unsuspecting expatriates residing in Singapore and China.
Apparently the pursuit of potential income has superseded the insurer's obligation to its shareholders and the public to do business only with ethical parties. Either that or RSA's due diligence process has failed miserably. What is unknown at this point is how RSA intends to explain this to the Chinese and Singaporean insurance regulators, and why they are putting their entire business operation in those jurisdictions at risk for the sake of a relatively small amount of potential income.
Comments from insurance regulators will be posted here as they become available.
More Details: Click Here
The tie-up is allegedly to sell Interglobal Insurance to unsuspecting expatriates residing in Singapore and China.
Apparently the pursuit of potential income has superseded the insurer's obligation to its shareholders and the public to do business only with ethical parties. Either that or RSA's due diligence process has failed miserably. What is unknown at this point is how RSA intends to explain this to the Chinese and Singaporean insurance regulators, and why they are putting their entire business operation in those jurisdictions at risk for the sake of a relatively small amount of potential income.
Comments from insurance regulators will be posted here as they become available.
More Details: Click Here
Tuesday, August 15, 2006
Interglobal Setting Its Brokers Up For A Fall
Employing typical Mike Henry-Steve Nichols trickery, Interglobal Limited, the business they illegally control, is attempting to stealthily knife its brokers in the back.
On the Interglobal website, prospective customers are encouraged to bypass their broker and sign up direct, using a term they call 'Execution Only Customers'. What this means is that customers sign up direct with Interglobal, thus cutting the brokers out of the deal. Mike Henry tried a similar dirty tactic against Mike Henry Travel Insurance agents a few years ago in New Zealand when he ran TV advertising. In these ads, Henry displayed the Mike Henry Travel Insurance web address, and viewers were instructed to go to Mike Henry's website and sign up direct, thus cutting out the travel agents. This caused such a ruckus from travel agents that Mike Henry was forced under pressure to remove the web address from the TV spots, and replaced it with text and a voice-over which stated: "See your bonded travel agent".
Can Henry and Nichols can get away with yet another slimy trick against those who have built the business they control? That will be determined by whether or not the brokers put up with it. It wouldn't be the first time Mike Henry and Steve Nichols stole from people who were mislead into believing that Mike Henry is a legitimate and honest businessman.
See: http://www.interglobalpmi.com/ig_index.php

Well, not quite so stealthily, if the brokers are paying any attention to what's going on.
On the Interglobal website, prospective customers are encouraged to bypass their broker and sign up direct, using a term they call 'Execution Only Customers'. What this means is that customers sign up direct with Interglobal, thus cutting the brokers out of the deal. Mike Henry tried a similar dirty tactic against Mike Henry Travel Insurance agents a few years ago in New Zealand when he ran TV advertising. In these ads, Henry displayed the Mike Henry Travel Insurance web address, and viewers were instructed to go to Mike Henry's website and sign up direct, thus cutting out the travel agents. This caused such a ruckus from travel agents that Mike Henry was forced under pressure to remove the web address from the TV spots, and replaced it with text and a voice-over which stated: "See your bonded travel agent".
Can Henry and Nichols can get away with yet another slimy trick against those who have built the business they control? That will be determined by whether or not the brokers put up with it. It wouldn't be the first time Mike Henry and Steve Nichols stole from people who were mislead into believing that Mike Henry is a legitimate and honest businessman.
See: http://www.interglobalpmi.com/ig_index.php
Subscribe to:
Posts (Atom)